Desk: Uncategorized Desk
Published: September 20, 2026
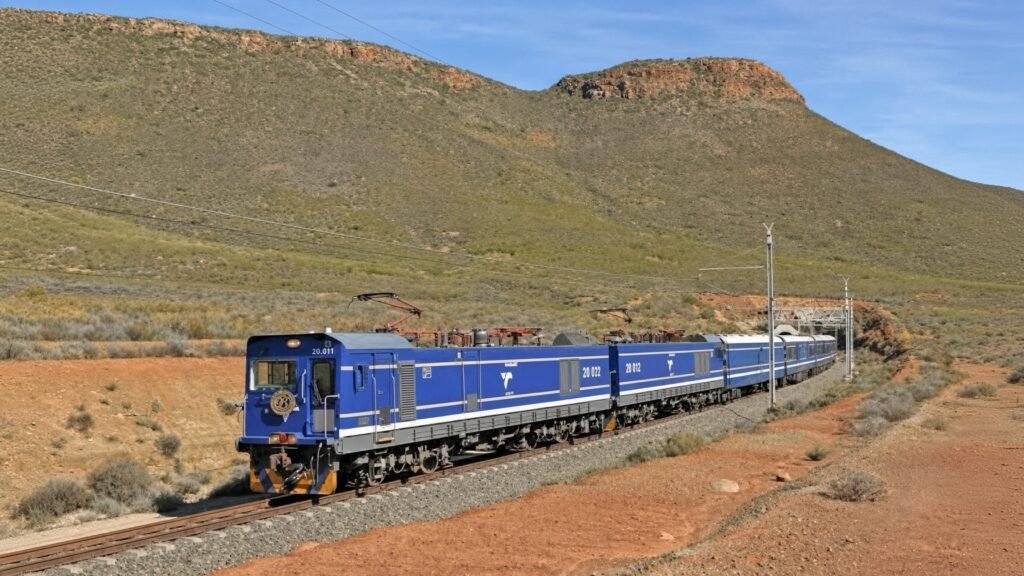
Zimbabwe’s US$115 million Afreximbank facility funds 10 locomotives and 315 wagons. That is the visible layer of rail recovery. The binding constraint on National Railways of Zimbabwe throughput is not rolling stock. It is permanent way. NRZ freight volumes have fallen to approximately 2 million tonnes in 2025, down from more than 12 million tonnes at the network’s historical peak, a contraction of roughly 83%. The US$115 million facility represents approximately 19.2% of the US$600 million NRZ itself says is required to modernise rolling stock and network infrastructure. The critical question the financing structure raises is not whether Zimbabwe needs locomotives. It is whether adding locomotives to track that cannot carry them at rated axle loads and speeds actually restores throughput, or simply moves the bottleneck from the equipment yard to the permanent way.
Zimbabwe is negotiating the facility with Afreximbank to purchase 10 locomotives and 315 wagons and to repair sections of the NRZ network. The proposed financing is significant in absolute terms and represents a genuine step toward restoring a critical piece of national logistics infrastructure. It is also smaller than the network’s stated rehabilitation requirement by a wide margin, and its composition, weighted toward rolling stock relative to permanent-way restoration, determines what the investment can actually deliver.
Analytical framing: This article distinguishes rolling stock (locomotives and wagons) from permanent way (track, bridges, signaling and drainage). Rolling stock consists of commodity assets that can be procured and delivered on commercial timelines. Permanent way consists of constructed assets that require multi-year civil works and cannot be accelerated by procurement alone. The thesis that Zimbabwe’s rail constraint sits primarily in permanent way rather than rolling stock is an LBNN and Limitless Beliefs Consulting analytical interpretation based on the disclosed facility composition and NRZ’s own stated investment need. It is not an official NRZ or Afreximbank classification.
Sources: National Railways of Zimbabwe, Zimbabwe Ministry of Transport reporting • Analysis: Limitless Beliefs Consulting • Note: Peak refers to NRZ’s highest recorded annual freight throughput. The 2025 figure reflects reported volumes for the year.
The Collapse Was Not a Rolling Stock Problem, So Rolling Stock Cannot Fix It
Zimbabwe’s rail freight contraction is not the arithmetic of losing locomotives. It is the arithmetic of losing the physical conditions that let locomotives run. During the extended period of NRZ’s underinvestment, the constraints that accumulated were primarily in permanent way: track geometry degradation, axle-load restrictions on key segments, bridge load-rating reductions, signaling failures and drainage damage that forces seasonal speed restrictions. Each of those operates on the network’s capacity independently of how many locomotives are available to run on it.
This distinction matters for the facility’s economic logic. A locomotive that cannot operate at rated speed because of a permanent-way restriction produces less throughput per unit than the same locomotive would on rehabilitated track. A wagon fleet that cannot be loaded to rated capacity because of axle-load limits on bridges generates less revenue per axle-kilometre. Adding 10 locomotives and 315 wagons to a network operating under those restrictions partially increases train count while leaving tonnes per train constrained by the physical layer below.
The most useful way to express the recovery equation is in throughput terms rather than asset terms. At historical peak, NRZ moved more than 12 million tonnes annually. It currently moves approximately 2 million tonnes. The facility’s rolling-stock component supports the operation of trains. It does not by itself restore the track and bridge capacity that determines how heavy those trains can be and how fast they can run. If the permanent-way constraint is not addressed in parallel, the rolling stock addition produces an increment to throughput, but not the order-of-magnitude recovery the network requires.
“Ten locomotives on track that cannot carry them at rated speed do not restore throughput. They redistribute the bottleneck from the equipment yard to the permanent way.”
The $115 Million Is 19.2% of Stated Need, and Its Composition Determines What It Delivers
NRZ has stated a total modernisation requirement of approximately US$600 million covering rolling stock, permanent way, signaling, workshops and related infrastructure. The US$115 million Afreximbank facility under negotiation represents approximately 19.2% of that total. The arithmetic gap of roughly US$485 million remains unfunded by this facility and would need to be addressed through additional capital sources, whether further development finance, public budget allocation, private concession capital or blended structures.
The more consequential variable is how the US$115 million is allocated within that structure. The disclosed uses are rolling stock (10 locomotives, 315 wagons) and “rail infrastructure repairs.” The public information reviewed for this analysis does not specify the split between those two categories. That ambiguity matters because the two components have very different economic profiles: rolling stock is a commodity procurement that can be delivered and commissioned within a single budget cycle, while permanent-way restoration is a construction program that typically takes multiple years per corridor and requires different financing instruments, procurement processes and supervisory capacity.
Sources: National Railways of Zimbabwe, Afreximbank facility disclosure • Analysis: Limitless Beliefs Consulting • Note: The US$600M represents NRZ’s total stated modernisation requirement. The undisclosed split between rolling stock and permanent-way restoration within the US$115M facility is a key variable in the facility’s economic outcome.
The Demand Anchor Is Mining, and Mining Requires Specific Corridors, Not the Whole Network
The rail investment is not occurring in a demand vacuum. Zimbabwe’s mining sector, particularly lithium, platinum-group metals, chrome and coal, generates bulk freight demand that rail is structurally suited to serve at lower cost than road. The corridor logic connects Zimbabwe’s interior mines to the Mozambican ports at Beira and Maputo, which historically handled the largest share of NRZ’s transit freight.
That corridor orientation changes the sequencing calculus. If the investment priority is restoring export corridors rather than the full domestic network, then the relevant question is not how many locomotives operate nationally, but whether the specific corridors from mine to port can physically carry the axle loads and support the train frequencies that mining volumes require. Corridor-specific permanent-way rehabilitation may therefore be a more economically efficient use of marginal capital than network-wide rolling-stock additions, because the corridor is where the revenue is concentrated.
The lithium cycle adds a second consideration. Lithium concentrate is a newly significant export commodity for Zimbabwe, and the volumes involved in a mature lithium export program would require rail capacity that currently does not exist. If the corridor is not rebuilt to lithium-relevant specifications (axle loads, bridge ratings, terminal handling at the port end), the export volumes will move by road, which is materially more expensive per tonne-kilometre and generates its own congestion, road-damage and safety costs. The rolling stock being purchased is therefore a bet on future demand. The permanent way is the bet on whether that demand can actually be served.
Currency Risk and the Financing Structure: The Dollar-Denominated Constraint
The facility is denominated in US dollars, consistent with Afreximbank’s standard practice for hard-currency infrastructure lending. NRZ’s revenue base, however, is generated predominantly in local currency, specifically ZWG and USD-denominated freight tariffs where applicable. This creates a structural currency mismatch between debt service obligations (in USD) and operating revenues (partly in ZWG), which increases the effective debt burden if the local currency depreciates against the dollar over the facility’s tenor.
Zimbabwe’s monetary environment compounds this in ways that are specific to its recent history. The country operates a multi-currency system in which the Zimbabwe Gold (ZWG) currency was introduced in 2024 to replace the Zimbabwean dollar, following a period of extreme currency instability. Freight tariffs are partly set in USD terms to protect revenue from currency erosion, but the broader cost structure, meaning labour, fuel, maintenance and local services, is largely in local currency. The mismatch between USD-denominated debt service and mixed-currency operating cash flow is a variable that determines whether the facility improves NRZ’s financial position or adds a hard-currency claim on a soft-currency revenue base.
The economics of the facility therefore depend not only on whether the physical assets improve throughput, but on whether the resulting revenue, in the currency mix in which NRZ actually earns, is sufficient to service the dollar-denominated debt across the facility’s amortisation period. If throughput recovery is slower than debt service obligations, the facility structure itself becomes a balance-sheet constraint that limits future investment capacity.
Sources: LBNN analytical framework informed by NRZ disclosed investment requirements and standard railway rehabilitation sequencing • Analysis: Limitless Beliefs Consulting • Note: This is an analytical representation, not an audited allocation of NRZ’s capital plan. The purpose is to illustrate the sequencing problem when rolling stock is funded ahead of permanent way.
Timeline Mismatch: Rolling Stock Deploys Before Track Is Ready
The facility’s structure embeds a timeline mismatch that is not obvious from the headline number. Rolling stock procurement, even accounting for manufacturer lead times, can typically be delivered and commissioned within 12 to 24 months. Permanent-way rehabilitation on a multi-corridor network is a 5 to 10 year civil works program that must be sequenced across funding cycles, engineering capacity and operational windows when track possession can be granted without stopping freight.
The consequence is that the 10 locomotives and 315 wagons will be available to operate before the track beneath them has been brought back to a condition that lets them run at rated efficiency. That is not a reason to delay rolling stock procurement. The assets are needed regardless, and early acquisition removes one future constraint. It is a reason to be precise about what the facility can and cannot deliver in its first years of operation. Rolling stock purchased now and operated on restricted track produces incremental throughput. It does not produce the throughput that the same rolling stock would produce on rehabilitated track.
The economic test therefore becomes whether the incremental throughput produced by the new rolling stock generates enough revenue to service the facility’s debt service during the period in which the permanent-way constraint is still binding. If it does, the facility is financeable on its own economics. If it does not, the facility requires either additional capital to accelerate the permanent-way work, or a debt structure with a grace period long enough to allow the permanent-way program to catch up.
Sources: LBNN Intelligence, NRZ, Afreximbank • Analysis: Limitless Beliefs Consulting
Sources: LBNN Intelligence, NRZ, Afreximbank, Zimbabwe Ministry of Transport • Analysis: Limitless Beliefs Consulting
The Facility Is Necessary but Not Sufficient: What the Recovery Actually Requires
Zimbabwe’s rail investment challenge is not fundamentally a rolling stock shortage. It is a permanent way condition problem that has accumulated over more than two decades of underinvestment, compounded by currency instability, deferred maintenance and the collapse of domestic logistics demand during the network’s lowest-utilization years. The US$115 million facility addresses the rolling-stock component. That is a necessary step, but it does not, on its own, restore the physical layer that determines what those locomotives and wagons can actually do.
The facility’s economic value will therefore be determined less by the quantity of assets delivered and more by three variables: whether the permanent-way constraint is addressed in parallel (through additional capital, corridor prioritization or blended structures), whether the demand from mining corridors materialises at the volumes that justify the investment, and whether the facility’s debt structure (dollar-denominated, partly sovereign-guaranteed, with a defined amortisation schedule) matches the operational recovery timeline rather than pre-empting it.
The most analytically useful metric for the next phase is not locomotive count or wagon count. It is corridor specific revenue tonne-kilometres, meaning the actual physical throughput generated on the specific lines the investment is intended to serve, tracked against the debt service schedule the facility creates. If those two curves converge on a viable trajectory, the facility will have done its job. If they diverge, with throughput recovering more slowly than the debt service claim, the facility will have funded the visible layer of a recovery that the permanent way cannot yet support.
Bottom Line: Zimbabwe’s US$115 million Afreximbank facility buys 10 locomotives and 315 wagons for a network operating at roughly 2 million tonnes of freight against a historical peak of more than 12 million tonnes, a contraction of approximately 83%. The facility represents approximately 19.2% of NRZ’s stated US$600 million modernisation need, leaving roughly US$485 million unfunded. The critical analytical point is not the size of the facility but its composition. Rolling stock is a procurement asset that can be delivered in 12 to 24 months. Permanent-way restoration, meaning track geometry, bridge ratings, axle-load capacity and signaling, is a multi-year civil works program that determines whether the rolling stock can operate at rated efficiency. The public disclosure does not specify the split between the two within the facility, and that undisclosed allocation is the single most important variable in the investment’s economic outcome. The demand side is real. Lithium, chrome, coal and PGM export corridors to Beira and Maputo provide a genuine freight base. But the corridor infrastructure that would carry those volumes at scale is not fully in place. The currency structure introduces a further constraint: USD-denominated debt service against a revenue base that is partly in local currency creates a mismatch that throughput recovery must outrun for the facility to be self-financing. The facility is necessary. Whether it is sufficient depends on whether the permanent-way constraint is addressed alongside it, and the disclosed facility structure does not yet establish that it is.
Data Qualification: This article combines railway sector and financing information from National Railways of Zimbabwe disclosures, the Zimbabwe Ministry of Transport reporting and the proposed Afreximbank facility as reported. The US$115 million facility is described as under negotiation at the time of writing. The facility has not been confirmed as closed, and the final terms, including tenor, pricing, guarantee structure and allocation between rolling stock and permanent way, may differ from the reported structure. The US$600 million figure represents NRZ’s own stated modernisation requirement for rolling stock, permanent way, signaling and related infrastructure. The approximately 2 million tonnes 2025 freight figure reflects reported NRZ volumes for the year. The historical peak of more than 12 million tonnes reflects the network’s highest recorded annual throughput, which occurred in a period of different infrastructure condition, tariff regime and demand composition. The 11% capacity figure referenced in some reporting may reflect a different metric than the freight tonnage comparison used here. This article anchors on the freight tonnage data because it is more directly disclosed. The analytical framing that separates rolling stock from permanent way as distinct investment layers, and that treats the sequencing of these layers as the primary economic variable, is an LBNN and Limitless Beliefs Consulting interpretive framework based on standard railway rehabilitation sequencing and the disclosed facility composition. It is not an official NRZ or Afreximbank classification. The 12 to 24 month rolling stock delivery window and multi-year permanent-way restoration timelines reflect typical rail sector practice and are illustrative rather than project-specific. Currency risk analysis reflects the general structure of USD-denominated infrastructure lending against mixed local-currency revenue. The specific facility’s currency structure is not disclosed. Derived calculations are identified as Limitless Beliefs Consulting calculations and are not official forecasts.