Desk: Uncategorized Desk
Published: September 17, 2026
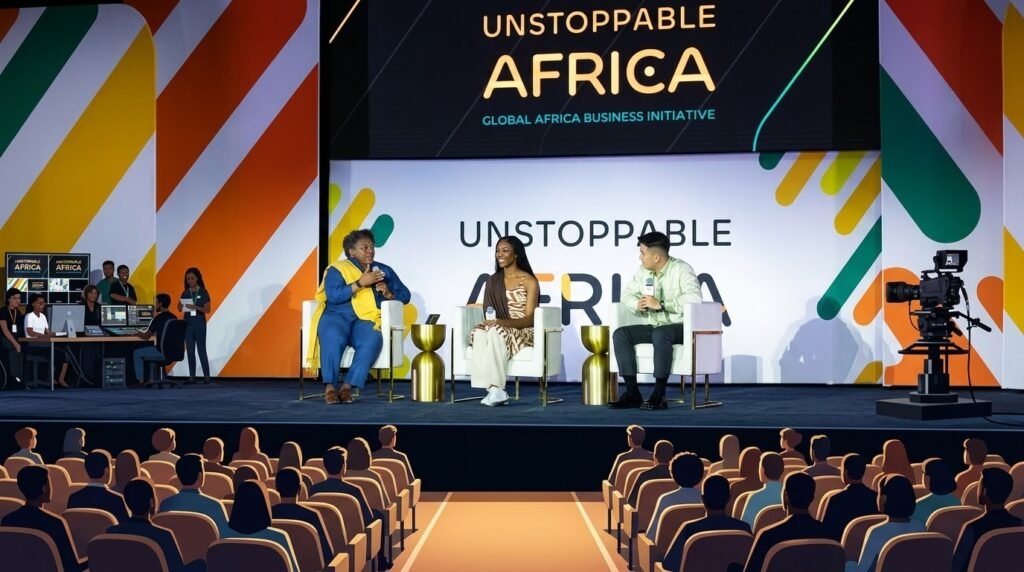
The fashion discussion at Unstoppable Africa 2026 is moving beyond design and cultural visibility toward a harder economic question: whether Africa can convert creativity, cotton, manufacturing capacity and consumer demand into larger domestic and regional value chains. Unstoppable Africa 2026 will bring more than 2,000 African and global business leaders and heads of state to New York on September 20–21 under the theme “Powering Business, Scaling Economies, Shaping the Future.” The event is convened by the United Nations and African Union and organized by the UN Global Compact as the flagship gathering of the Global Africa Business Initiative. For fashion, the most important feature is not the presence of fashion executives at an international conference. It is the structure of the discussion. The official 2026 programme includes a dedicated session titled “The Price of Nice: How Can Africa Win the Global Thread Wars?”, examining ultra-fast fashion, African manufacturing, repair, resale, rental, upcycling, climate smart textiles and digital platforms connecting artisans with global markets.
The panel includes Omoyemi Akerele, Founder and CEO of Lagos Fashion Week and Style House Files; Temwa Gondwe, Director of Creatives and Diaspora at Afreximbank; designer Kenneth Ize; and Amira Rasool, Founder and CEO of The Folklore. The economic backdrop is substantial but uneven. The African Development Bank has previously estimated the Sub-Saharan African apparel and footwear market at approximately $31 billion, while its Fashionomics research estimated the global fashion industry at approximately $1.3 trillion. The same research found that approximately 90% of African fashion businesses are SMEs and identified lack of capital, skills and industrialization as structural constraints.
Africa’s fashion economy does not primarily face a demand problem. It faces a value capture problem. The strategic question is how much of the economic value generated by African design, cotton, textiles, manufacturing, distribution and consumer demand remains within African businesses rather than being captured elsewhere in the global supply chain. Africa produces approximately 6% of the world’s cotton, yet much of the continent’s textile demand continues to depend on imported fabrics and other inputs. The gap between agricultural production and finished textile production is a major source of lost value addition.
Sources: African Development Bank, Fashionomics Africa • Analysis: Limitless Beliefs Consulting
“Africa’s fashion economy does not primarily face a demand problem. It faces a value capture problem. The question is how much of the economic value generated by African design, cotton, textiles, manufacturing and consumer demand remains within African businesses.”
The Supply Chain Is the Economic Bottleneck Cotton to Consumer
Africa produces approximately 6% of the world’s cotton according to African Development Bank research, yet much of the continent’s textile demand continues to depend on imported fabrics and other inputs. The economic chain is straightforward: cotton becomes yarn, then fabric, then dyed material, then garments, then branded products, then distribution, then retail. Each additional stage can create employment, industrial demand, tax receipts and export revenue. If cotton leaves the continent as a raw commodity and finished garments return as imports, much of the potential value creation occurs outside the producing economy.
UNCTAD reported that African apparel exports averaged nearly $9 billion annually during 2015–2017, representing approximately 2% of global apparel exports. Although the historical period is older than the current 2026 market, the statistic remains useful as a structural benchmark because it demonstrates the scale of Africa’s participation in global apparel trade relative to the size of its population and raw material base. More recent trade evidence shows that the sector remains exposed to external demand and policy conditions. UNCTAD reported that global trade in apparel and clothing accessories fell 13% in 2023, illustrating that fashion manufacturing is not insulated from global consumption cycles.
Sources: AfDB Fashionomics Africa, UNCTAD, Afreximbank • Analysis: Limitless Beliefs Consulting
Trade Preferences Matter The AGOA Evidence
The International Trade Centre reported that in 2024, 96.5% of eligible African apparel and textile exports under AGOA entered the United States using AGOA preferences. Utilization was particularly high in Benin at 99.3%, Lesotho at 98.7% and Kenya at 92.9%. This matters because market access can influence the location of production. A manufacturer does not compare labor costs alone. It compares labor, electricity, logistics, tariff treatment, rules of origin, financing costs, delivery times and reliability.
For fashion, a regional clothing manufacturer does not need to sell exclusively into Europe or North America. It can build demand across African markets if payment systems, customs procedures, logistics and trade finance allow garments to move at commercially competitive costs. Afreximbank reported that intra-African trade reached $220.3 billion in 2024, increasing 12.4% from the previous year. Total African merchandise trade increased 13.9% to approximately $1.5 trillion. Africa nevertheless represented only about 3.3% of global exports.
Sources: International Trade Centre Trade Briefs • Analysis: Limitless Beliefs Consulting
Symmetrical Economic Impact Who Gains, Who Absorbs Risk
Sources: LBNN Intelligence, AfDB, UNCTAD • Analysis: Limitless Beliefs Consulting
Capital Allocation The Industrial Benchmark
The most useful comparison for African fashion is not simply another African fashion brand. It is the industrial performance of countries that have successfully converted agricultural inputs and labor into export oriented manufacturing. Vietnam provides a relevant benchmark. The African Development Bank has highlighted Vietnam’s export diversification as an example of movement from lower value production toward more complex manufacturing. In 2020, Vietnam exported approximately $15.5 billion of clothing and accessories.
That figure is important because it illustrates the difference between having a fashion market and having a globally competitive apparel manufacturing system. The comparison should not be interpreted as evidence that Africa lacks fashion demand or design capability. It demonstrates that production scale, supplier ecosystems, trade policy, infrastructure and manufacturing finance can matter as much as creative output.
The AfDB’s FAIR programme provides one example of this direction. It is structured as a seven year programme with a direct target size of $10 million and an objective of mobilizing up to $70 million in follow on investment for women led SMEs operating in cultural and creative industries, including fashion. That ratio implies a potential mobilization target of approximately $7 of follow on investment for every $1 of direct programme capital. This is a programme design target, not a realized investment return.
Sources: African Development Bank, UNCTAD • Analysis: Limitless Beliefs Consulting
What Institutional Capital Should Measure
For investors evaluating African fashion and textile opportunities, the most relevant metrics are not brand visibility or runway presence. They are the same metrics that determine whether any industrial business can scale: gross margin (revenue minus direct cost of goods sold), inventory turnover (how quickly inventory is sold and replaced), working capital cycle (the period between paying suppliers and collecting cash from customers), and yield spread (the difference between an investment’s expected yield and a relevant benchmark yield).
The most investable opportunities may sit outside the fashion label itself. These include textile manufacturing, fabric production, dyeing facilities, garment factories, industrial parks, logistics, warehousing, digital commerce, payments, inventory finance, trade finance, recycling and resale infrastructure. This is consistent with AfDB’s value chain approach, which emphasizes the economic contribution created across production rather than treating fashion exclusively as a design activity.
Investment and Policy Watchlist Eight Indicators That Determine the Outcome
- Local Input Content: Track the percentage of textile and apparel inputs sourced domestically or regionally. Higher local input content improves the foreign exchange economics of export manufacturing.
- Factory Utilization: Monitor utilization of spinning, weaving, dyeing and garment facilities. New factories create limited economic value when utilization remains structurally low.
- Export Value: Track apparel and textile exports by country rather than relying on brand visibility as a proxy for industrial growth.
- Working Capital Access: Measure the cost and availability of trade finance, inventory finance and SME credit, particularly for women led enterprises.
- Intra-African Trade: Monitor whether fashion products become a larger component of the $220.3 billion intra-African trade base reported for 2024.
- Circular Economy Capacity: Track repair, resale, recycling and textile recovery capacity rather than measuring sustainability only through brand commitments.
- Intellectual Property Ownership: Measure whether African designers and manufacturers retain trademarks, designs, licensing revenue and distribution economics.
- Regional Trade Friction: Monitor customs delays, tariffs, non-tariff barriers and rules of origin because logistics costs can eliminate otherwise competitive manufacturing advantages.
Value Capture, Not Creative Output, Is the Real Test
Unstoppable Africa 2026 places African fashion inside a broader conversation about ownership, trade, capital and industrial development. That shift matters because the economic problem facing the sector is not simply how to produce more fashion. It is how to capture more of the value generated by fashion inside African economies. The available data show both the scale and the limitation of the opportunity. AfDB estimates have placed the Sub-Saharan African apparel and footwear market at approximately $31 billion, while its research identifies SMEs as approximately 90% of African fashion businesses. UNCTAD has previously measured African apparel exports at approximately $9 billion annually during 2015–2017, equivalent to around 2% of global apparel exports.
At the same time, Africa’s broader trade position is changing. Afreximbank reported that intra-African trade reached $220.3 billion in 2024, up 12.4%, while total African merchandise trade rose to approximately $1.5 trillion. That creates a larger potential regional market for African-made clothing, textiles and accessories. The challenge is converting that market into production. Capital must reach manufacturers, not only designers. Trade finance must support inventory. Industrial parks must achieve utilization. Power and logistics costs must remain competitive. Intellectual property must remain with African businesses where possible. And regional trade rules must allow garments and textiles to cross borders at costs that support commercially viable production.
Bottom Line: Unstoppable Africa 2026 places African fashion inside a global capital conversation and the economics reveal a value capture problem, not a demand problem. Africa’s Sub-Saharan apparel and footwear market is estimated at $31 billion against a $1.3 trillion global fashion industry. 90% of African fashion businesses are SMEs. Africa produces 6% of the world’s cotton, yet imports most of its finished textiles. AGOA utilization for apparel and textiles is 96.5%, proving trade preferences matter but only when the manufacturing base exists to use them. Vietnam exported $15.5 billion of clothing in 2020; African apparel exports averaged $9 billion annually in 2015–2017. The gap is industrial capacity, trade finance, infrastructure and value chain depth. The panel at Unstoppable Africa 2026 asks whether Africa can move from being a source of creative influence and raw materials to becoming a larger owner of the manufacturing, intellectual property, distribution and financial value created by fashion. The answer will be visible in factory utilization, export receipts, local input content, inventory turnover, SME financing, regional trade volumes and the share of fashion value chains controlled by African businesses not in runway visibility.