Desk: Uncategorized Desk
Published: September 19, 2026
Nigeria’s 3,700 tower programme is not, fundamentally, a build volume story. It is a density selection problem. The Federal Government intends to activate at least 200 telecommunications sites before December, targeting more than 20 million Nigerians who currently lack adequate service, with each tower expected to reach 5,000 to 10,000 residents. Run that arithmetic and a single threshold emerges: at 3,700 towers, reaching 20 million requires an average of approximately 5,405 residents per site. The government’s own lower planning assumption 5,000 per tower falls below that threshold, producing a reach of 18.5 million. The high-end assumption produces 37 million. Which end of that range the programme actually lands on will be determined not by how many towers get built, but by where they are placed and the unserved population is concentrated precisely in the rural, low density locations where the threshold is hardest to clear.
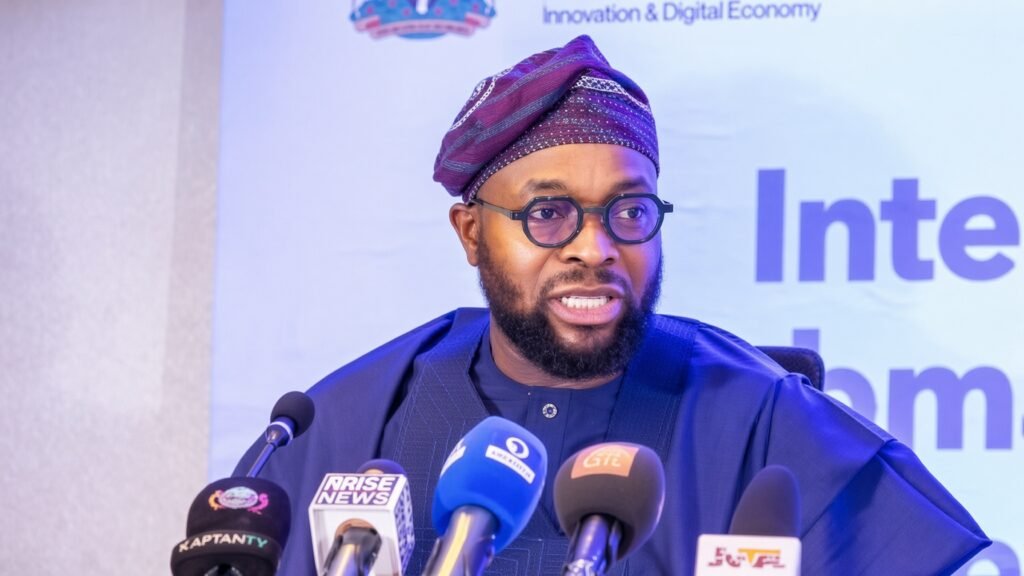
Communications, Innovation and Digital Economy Minister Bosun Tijani said the Federal Government intends to activate at least 200 new telecommunications sites before December as part of a national plan to deploy approximately 3,700 towers. The programme is designed to reach more than 20 million Nigerians who currently lack adequate telecommunications services.
That creates an important capacity test, and the test is arithmetic. If every tower reaches the stated 5,000 to 10,000 resident range, 3,700 towers could theoretically cover between 18.5 million and 37 million residents. The first 200 towers, under the same assumption, would directly correspond to roughly 1 million to 2 million residents approximately 5.4% of the total planned programme.
Analytical framework note: The 5,405 residents per tower figure is not a government target or an official programme assumption. It is a break even threshold derived by dividing the 20 million unserved target by the 3,700 tower programme. Actual coverage will depend on tower location, radio propagation, terrain, spectrum, backhaul capacity, overlapping network footprints and the distribution of the unserved population across Nigerian states.
Sources: Federal Ministry of Communications, Innovation and Digital Economy, LBNN Intelligence • Analysis: Limitless Beliefs Consulting
The Programme Only Reaches Its Target Above a Density It Does Not Fully Control
Read the threshold carefully. The government’s own low end planning assumption 5,000 residents per tower produces 18.5 million reachable residents across 3,700 sites. That is approximately 1.5 million below the stated 20 million target. The high end assumption 10,000 residents per tower produces 37 million, comfortably exceeding the target. Every outcome between those poles is arithmetically possible.
The programme’s stated objective therefore carries an implicit density requirement, even though the government has not framed it that way. Reaching 20 million requires the average site to serve roughly 5,405 residents. That is a modest but material lift above the lower bound of the government’s own assumption approximately 8% higher than the floor.
Where the towers are actually placed is what determines which side of that line the programme lands on. And that is where the economics become difficult. The 20 million unserved Nigerians are not evenly distributed. They are disproportionately located in rural areas, which is where population density is lowest by definition. If the programme prioritizes reach going to the most remote communities first average density per site falls and the target becomes harder to hit. If the programme prioritizes volume maximizing residents reached per tower it may serve communities that already have partial coverage while leaving the hardest to reach populations unserved.
“Reaching 20 million with 3,700 towers requires average site density of roughly 5,405 residents. That is not a construction target. It is a placement decision and the two objectives are in tension.”
Coverage Is Broad Usage Is the Constraint
Nigeria already has extensive mobile network coverage by global standards, but coverage averages can conceal geographic gaps and, more importantly, can conceal the difference between a signal and meaningful connectivity. ITU data show that 95.3% of Nigeria’s population was covered by at least a 2G network in 2024, 89.4% by at least 3G and 84.6% by at least LTE/WiMAX. Yet only 41.2% of the population used the internet, and active mobile broadband subscriptions stood at 41.4 per 100 people.
The gap between LTE coverage and internet use more than 43 percentage points is the real constraint on the programme’s economic impact. A signal can reach a community without translating into meaningful digital participation if households cannot afford devices or data, if electricity is unreliable, or if the available network has insufficient capacity. This is why the 3,700 tower programme’s success depends on more than build execution: even a fully deployed network will not close the digital divide if the affordability layer remains untouched.
Sources: International Telecommunication Union (ITU) DataHub, 2024 • Analysis: Limitless Beliefs Consulting
The Unserved Live Where Density Is Lowest Africa’s Rural Gap
The density problem does not exist in isolation. ITU estimates that 57% of Africa’s urban population used the internet in 2024, compared with only 23% of the rural population a 34 percentage point gap. Nigeria’s national internet use rate of 41.2% sits between those poles, but the internal distribution almost certainly mirrors the broader regional pattern. The communities the 3,700 tower programme is designed to reach are concentrated in the low density, low usage, harder to monetize portion of that distribution.
This is the structural bind. The programme’s arithmetic viability depends on clearing a density threshold. The populations the programme exists to serve are located in areas where that threshold is least likely to be cleared. That does not make the programme unviable universal service programmes routinely accept below commercial returns in exchange for social and economic externalities. But it does mean the government cannot measure the programme’s success through tower counts alone. The relevant metric is cost per newly connected resident, and that metric will rise as the programme moves into the areas it was designed to reach.
Sources: International Telecommunication Union (ITU) Datahub, 2024 • Analysis: Limitless Beliefs Consulting
Capital Costs Are High Density Economics Matter More
Telecommunications infrastructure is highly capital intensive. Tower construction requires civil works, radio equipment, power systems, batteries or other backup, transmission equipment, site acquisition and ongoing maintenance. Rural sites carry additional costs because population density is lower while power and transport infrastructure are often weaker.
Nigeria’s monetary environment remains restrictive. The Central Bank of Nigeria maintained its Monetary Policy Rate at 26.5% in July 2026 and retained the Cash Reserve Requirement for deposit money banks at 45%. The IMF projects Nigerian real GDP growth of 4.1% in 2026, with annual-average consumer-price inflation of 16.0% and end-period inflation of 17.0%.
For infrastructure investors and telecom operators, a 26.5% benchmark policy rate matters because commercial borrowing costs are generally higher than the central bank’s policy rate. Long-duration tower and fibre projects therefore require sufficient expected cash flow to compensate for financing costs and operating risks. In that environment, the density threshold is not an abstract arithmetic point — it is the boundary between a project that can attract commercial capital and one that requires public subsidy to proceed.
Currency exposure compounds the challenge. Radio units, antennas, transmission equipment, batteries, power systems and network software are often priced or financed in foreign currency. A weaker naira increases the local-currency cost of imported equipment unless operators have sufficient dollar revenue or hedging arrangements. This is particularly relevant for a national rollout involving thousands of sites, because equipment procurement occurs before the assets generate recurring cash flow.
Three Layers Must Expand Together — Access, Backhaul, Power
The 3,700-site programme is being implemented against a broader national digital-infrastructure strategy. The Federal Government has separately announced plans for a 90,000-kilometre national fibre network intended to increase backbone connectivity and reduce the cost of moving traffic between communities.
The distinction between access and backbone infrastructure matters. Towers connect users to mobile networks. Fibre and other transmission infrastructure connect towers to the wider network. Power infrastructure keeps the sites operating. The three layers therefore have to expand together. A tower without dependable backhaul can provide coverage but limited data capacity. A fibre network without sufficient access sites can leave communities physically close to infrastructure but commercially disconnected. A tower and fibre connection without dependable power can produce unreliable service.
Nigeria’s connectivity problem, in other words, is not simply a shortage of towers. It is a coordination problem across radio access, backhaul, electricity, affordability and digital demand — each of which can separately constrain the economic return on the others.
Sources: LBNN Intelligence, ITU, CBN, IMF, Federal Ministry of Communications, Innovation and Digital Economy • Analysis: Limitless Beliefs Consulting
Sources: LBNN Intelligence, ITU, Federal Ministry of Communications, Innovation and Digital Economy • Analysis: Limitless Beliefs Consulting
The Real Test Is Which 20 Million Not How Many Towers
Nigeria’s 3,700 tower programme addresses a genuine structural weakness in the country’s digital economy: the difference between national network coverage and meaningful connectivity in underserved communities. The programme’s value is real, and the public financing it implies is defensible on standard universal service grounds rural connectivity carries externalities that commercial operators cannot capture in tower revenue alone.
But the programme’s arithmetic contains a tension the government has not explicitly resolved. Reaching 20 million with 3,700 towers requires average site density of roughly 5,405 residents. If the deployment prioritizes reaching the hardest to connect populations, average density falls below that line and the target becomes arithmetically unreachable at the planned tower count. If the deployment prioritizes clearing the threshold, the programme may serve populations that are already partially covered while leaving the most isolated communities unserved. The two objectives reach and volume are not fully compatible within a fixed tower budget.
The first 200 sites will function as an implementation test. If the government can activate them on schedule and connect them to dependable power and backhaul, it establishes the operational model for the remaining 3,500 sites. But the more important question is the placement pattern those 200 sites reveal. If they cluster in higher-density locations, the government is optimizing for the threshold. If they target the most isolated communities, it is optimizing for reach and the 20 million target will need to be revised, or the tower count increased, or the average density assumption revised upward.
The programme should ultimately be judged on more than tower counts. The key performance indicators are cost per newly connected resident, average site density, network availability, traffic per site, backhaul capacity, energy cost, data affordability and the amount of private capital subsequently attracted into the same communities. The decisive metric is not how many towers are built. It is which previously underserved Nigerians become reliably connected because those towers exist and whether the density that results is high enough to sustain the 20 million objective.
Bottom Line: Nigeria’s 3,700 tower programme is not really a construction story it is a density selection problem with a specific arithmetic threshold. Reaching 20 million unserved Nigerians with 3,700 towers requires average site density of roughly 5,405 residents. The government’s own lower planning assumption of 5,000 per tower produces 18.5 million 1.5 million short of the target while its upper assumption of 10,000 produces 37 million. The 200 sites targeted before December represent just 5.4% of the total programme. Every outcome between those poles is arithmetically live, and which one materializes will be determined by where the towers are placed, not by how many are built. That is the bind: the 20 million unserved Nigerians are concentrated in rural, low density areas where ITU data show African rural internet use sits at 23% against 57% urban and those are precisely the locations where the density threshold is hardest to clear. Coverage is not the binding constraint: 84.6% of Nigerians have LTE/WiMAX coverage but only 41.2% use the internet, a 43-point gap that the tower programme cannot close on its own. CBN’s 26.5% policy rate and 45% CRR mean commercial capital requires density above the threshold; below it, subsidy is required. The programme’s real test is not build execution. It is whether the government treats density as an objective variable it can optimize or an accident it discovers after the towers are standing.
Data Qualification: This article combines government programme information with telecommunications and macroeconomic data from the Federal Ministry of Communications, Innovation and Digital Economy, the International Telecommunication Union (ITU), the Central Bank of Nigeria (CBN) and the International Monetary Fund (IMF). The 5,405 residents-per-tower figure is an LBNN analytical threshold, derived by dividing the 20 million unserved target by the 3,700 tower programme, and is not a government target or planning assumption. The government’s stated assumption is a range of 5,000 to 10,000 residents per tower. Population-per-tower calculations assume no overlapping coverage; actual coverage depends on tower location, radio propagation, terrain, population distribution, spectrum, backhaul capacity and the geometry of deployed sites. The 90,000 kilometre fibre network figure refers to a separately announced national backbone programme and is not part of the 3,700 tower count. ITU coverage and internet use figures reflect 2024 data. CBN policy rates reflect the July 2026 Monetary Policy Committee decision. IMF projections reflect the 2026 Article IV consultation. Derived calculations are identified as Limitless Beliefs Consulting calculations and are not official forecasts.